Up to 53% offSee the plans

Back to articles | Analysis | Stocks

Farabi Pharma's Six-Month Profit Passed Its Whole Prior Year, but Operating Cash Is 37.6% of Profit; Entry Holds Up to 21,273 Rial (Monday 2 November 2026)

Sahmino Research Desk | 2 November 2026 | 10 min read

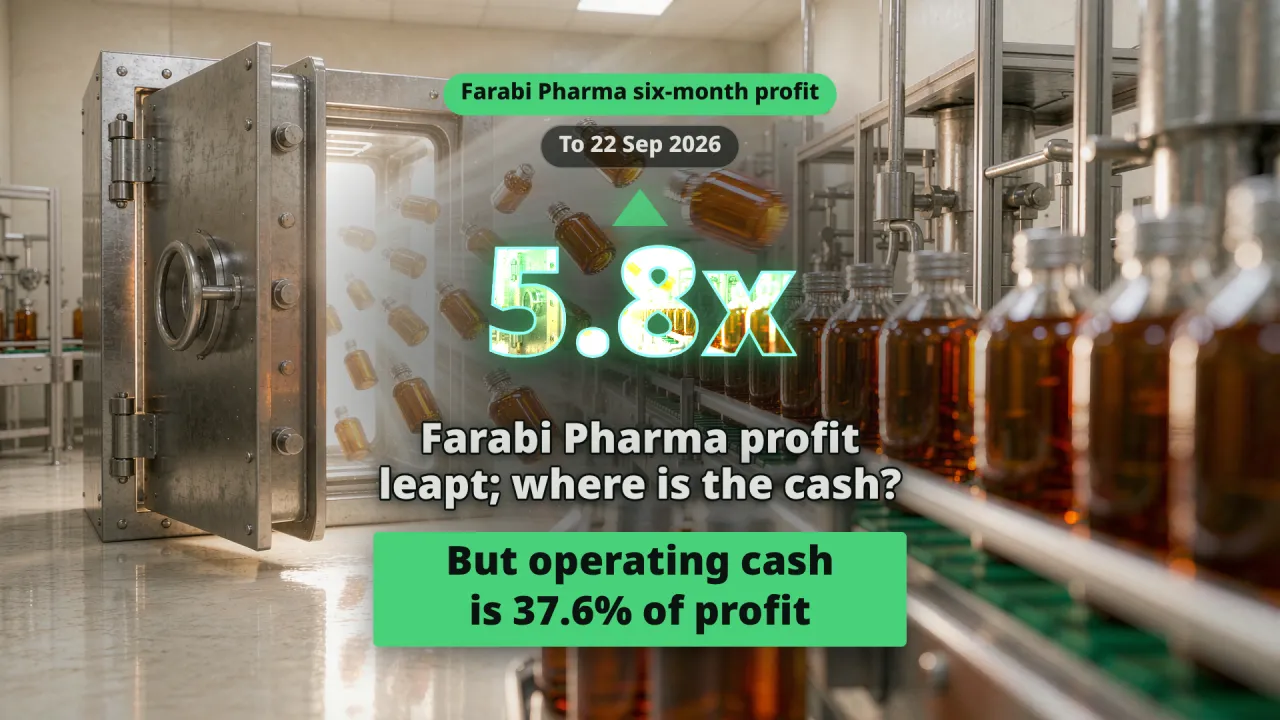
Farabi Pharmaceutical's standalone net profit for the six months to 22 September 2026 reached 16,341 billion rial, 5.8 times a year earlier and above all of fiscal 1404; but operating cash was 37.6% of profit and receivables rose 53%. Close on 1 November: 21,050 rial, P/E 6.58 against 10.53 for the industry. Sahmino desk: target 22,373…
DFRBup3.0%23,800rials11 November

Related video

Watch the full video

Farabi Pharmaceutical (DFRB) reported standalone net profit of 16,341 billion rial for the six months to 22 September 2026 (31 Shahrivar 1405). That is 5.8 times the 2,807 billion rial of the same period a year earlier and 2.6% above the profit of the whole of fiscal 1404, the year to 20 March 2026 (15,924 billion rial). The question is whether that profit turned into cash: operating cash flow was 6,144 billion rial, or 37.6% of profit. The answer has two halves. Monthly sales in Shahrivar and Mehr confirm the jump, but entry only makes sense up to a price where the reward still exceeds the risk: 21,273 rial.

The statements are filed in million rial and converted here to billion rial (1,000 million rial equals one billion rial).

Background

Farabi Pharmaceutical makes tablets, capsules and suspensions at a plant on the Shiraz road near Isfahan, and its fiscal year ends on 20 March (29 Esfand), according to its Codal issuer profile. The share trades on the first market of the Tehran Stock Exchange; registered capital is 9,206 billion rial, or 9.206 billion shares, and the exchange card (nightly reading of 31 October) puts free float at 37%. The six-month figures come from the unaudited standalone interim statement (tracing number 1609724, published 21 October 2026); the prior-year comparison columns are restated and audited. The assembly of 21 July 2026 approved a cash dividend of 930 rial a share for fiscal 1404, 53.8% of earnings per share of 1,730 rial (tracing number 1577007); at the 1 November close of 21,050 rial that is a cash yield of 4.4%.

The numbers

  • Revenue and margin: operating revenue was 39,911 billion rial against 17,928 (2.2 times). Gross profit was 21,963 against 5,327; gross margin 55.0% against 29.7%. Cost of sales rose 42% (17,948 against 12,601).
  • Profit: operating profit 21,119 against 4,401 (4.8 times); pre-tax profit 20,392; tax 4,051; net profit 16,341 against 2,807. Earnings per share were 1,775 rial against 305. Twelve-month EPS is 1,775 plus 1,730 minus 305, or 3,200 rial, matching the exchange card.
  • Volume and price (monthly activity report for Mehr, tracing number 1618885): domestic sales for the seven months to 22 October 2026 were 55,581 billion rial against 24,497 (2.3 times). Units sold were 7.4% higher for tablets, 15.0% lower for capsules and 12.5% lower for suspensions than in the same seven months a year earlier; the printed selling rate per unit was 2.2 times higher for tablets, 2.9 times for capsules and 1.9 times for suspensions.
  • Month by month: net sales for the first five months were 27,896 billion rial (a monthly average of 5,579), then 12,015 in Shahrivar (tracing number 1602515) and 12,530 in Mehr, both about 2.2 times the five-month average. Seven-month net sales are 52,441 billion rial, 2.3 times the 22,437 of the same seven months last year and 29% above all of fiscal 1404 (40,597).
  • Cash: net operating cash flow was 6,144 billion rial against negative 646 a year earlier, 37.6% of net profit. Sahmino's nightly twelve-month ratio is 48.5%.
  • Balance sheet, 22 September against 20 March 2026: trade and other receivables 53,703 against 35,062 (up 53%); inventory 16,498 against 8,372 (up 97%); trade payables 20,933 against 7,222 (up 190%). Cash is 1,034, financing facilities 5,477, dividends payable 14,277 and tax payable 5,408 billion rial.

Drivers and risks

Mechanism. Revenue is price times volume. Domestic sales rose 2.3 times while units of capsules and suspensions fell, so the average selling rate filled the gap. That is arithmetic; the statements do not say why the rates rose. Cost of sales rose 42% against revenue up 123%, and gross margin went from 29.7% to 55.0%. How long that margin lasts depends on future selling rates and costs; net sales in Shahrivar and Mehr were both above the five-month monthly average.

Risk one: cash. The gap between profit and operating cash is 10,197 billion rial. Over the same period receivables rose 18,640 and inventory 8,126 billion rial, while trade payables rose 13,711 (our subtractions from the balance sheet). Dividends payable are 13.8 times cash on hand; these balances alone do not show payment timing, but collecting receivables matters for turning profit into cash.

Risk two: input cost. In the Mehr report the purchase rate for domestic active ingredient in that month was 83.8 million rial per kilogram, 48% above the 56.8 million average to the end of Shahrivar, although Mehr purchases were about 50 tonnes against 254 tonnes before. If such rates reach cost of sales, a 55% gross margin comes under pressure; that is a condition to watch, not a forecast.

Risk three: price flow. Over the five sessions to 1 November (10 Aban) individual investors net sold 663 billion rial (Sahmino's recorded data) and the close slipped from 22,360 rial on 24 October to 21,050 rial on 1 November, 5.9% lower (base: the 24 October close). The 1 November close is 6.4% below the 52-week high (22,500 rial on 25 October; base: the high). Twenty-session buyer strength is 0.76: individual sellers' per-capita size exceeded buyers'.

Outlook

Valuation. Twelve-month EPS of 3,200 rial and the 1 November close of 21,050 rial give a P/E of 6.58; the pharmaceutical industry P/E on the exchange card (nightly reading of 31 October) is 10.53, so Farabi sits 37.5% below the industry (base: the industry multiple). Price to sales is 3.10 and price to book 5.77, both at the same 1 November close; reconstructed twelve-month return on equity is 87.8%. The adjusted price series is up 266% over six months, so today's relative cheapness followed from earnings growth rather than a price that lagged absolutely.

The desk's call. Since the session of 1 November 2026 the Sahmino desk has a buy on DFRB: reference price 21,050 rial, target 22,373, invalidation 20,174 rial, horizon 15 sessions, in a market regime labelled "falling, wild"; this type of call reached its target 8 times in a sample of 16 (a counted stance with no separate probability). The "flow turn" signal of 31 October claims the same target with a 83.7% chance (lower bound 66.3%); a random entry in the same regime has a 51.6% chance of that target. But the signal's reward-to-risk from today's last trade is only 0.54, so at that price it is no longer the signal's entry point. The desk's overall record: of 3,031 settled stances, 1,349 reached target, 1,474 were invalidated and 208 expired. Four earlier buy calls on this share, for the sessions of 3 to 6 October, were all invalidated; those four belong to one wave, not four independent samples.

Entry condition. The 1 November close (21,050 rial) is 5.9% below the target (base: the target) and 4.3% above the invalidation (base: the invalidation), a reward-to-risk of 1.51. Today, 2 November, the last trade read at 17:34 was 21,600 rial, taking the desk's ratio to 0.54; the close read at the same time was 21,390 rial and the ratio 0.81, and the exchange revises the close until about 22:00. Reward equals risk when the price is the midpoint of target and invalidation: (22,373 plus 20,174) divided by 2 is 21,273.5 rial; up to 21,273 rial the reward is larger than the risk (our calculation from the desk's target and invalidation). Above that, the price has already used part of the desk's reward.

Repeat this check in the Sahmino screener: P/E at most 0.9 times the industry's, annual profit growth above 30%, revenue growth above 20%, a positive desk stance and twenty-day traded value of at least 20 billion rial. In the 2 November reading (with derived readings rebuilt the night before) 29 of 2,153 listed symbols passed these conditions and Farabi was one of them. Price, individual and institutional flow and the desk's call are on the DFRB symbol page. For a profit jump that came from rates, read the Jam Piln report; for individual selling set against a desk call, the Mobarakeh Steel report.

Bottom line

Farabi's monthly sales have moved away from the first five months, but cash collection has not yet kept pace with profit: Shahrivar and Mehr were each about 2.2 times the first five months' monthly average, yet operating cash is 37.6% of profit and receivables rose 53%. Sahmino desk: DFRB stays above 20,174 rial and reaches 22,373 rial; condition: entry up to 21,273 rial, above which the reward is smaller than the risk; horizon: 15 sessions; invalidation: a daily close below 20,174 rial. Reading: 2 November 2026 (call of the 1 November session).

What to watch

  • The nine-month statement (to 21 December 2026): does operating cash move closer to profit and do receivables fall from 53,703 billion rial.
  • The Aban monthly report: monthly sales against Mehr's 12,530 billion rial and the active-ingredient purchase rate against 83.8 million rial per kilogram.
  • Individual and institutional flow on the symbol page and the daily close against 20,174 rial.
  • Re-running the screener filter after each new report to see whether Farabi is still on the list.

References

  1. CodalTracing 1609724: standalone six months to 22 September 2026, revenue 39,911,022, net profit 16,340,966, operating cash 6,144,419 million rial.Cited Nov 2, 2026
  2. CodalTracing 1618885: October reporting month net sales 12,530,001, seven-month total 52,441,023 million rial.Cited Nov 2, 2026
  3. CodalTracing 1602515: September reporting month net sales 12,015,429, first six months 39,911,022 million rial.Cited Nov 2, 2026
  4. SahminoDFRB: 1 November 2026 desk call, reference 21,050, target 22,373, invalidation 20,174 rial in 15 sessions; 2 November 17:34 exchange reading 21,390 rial, revisable.Cited Nov 2, 2026

Related articles